Services
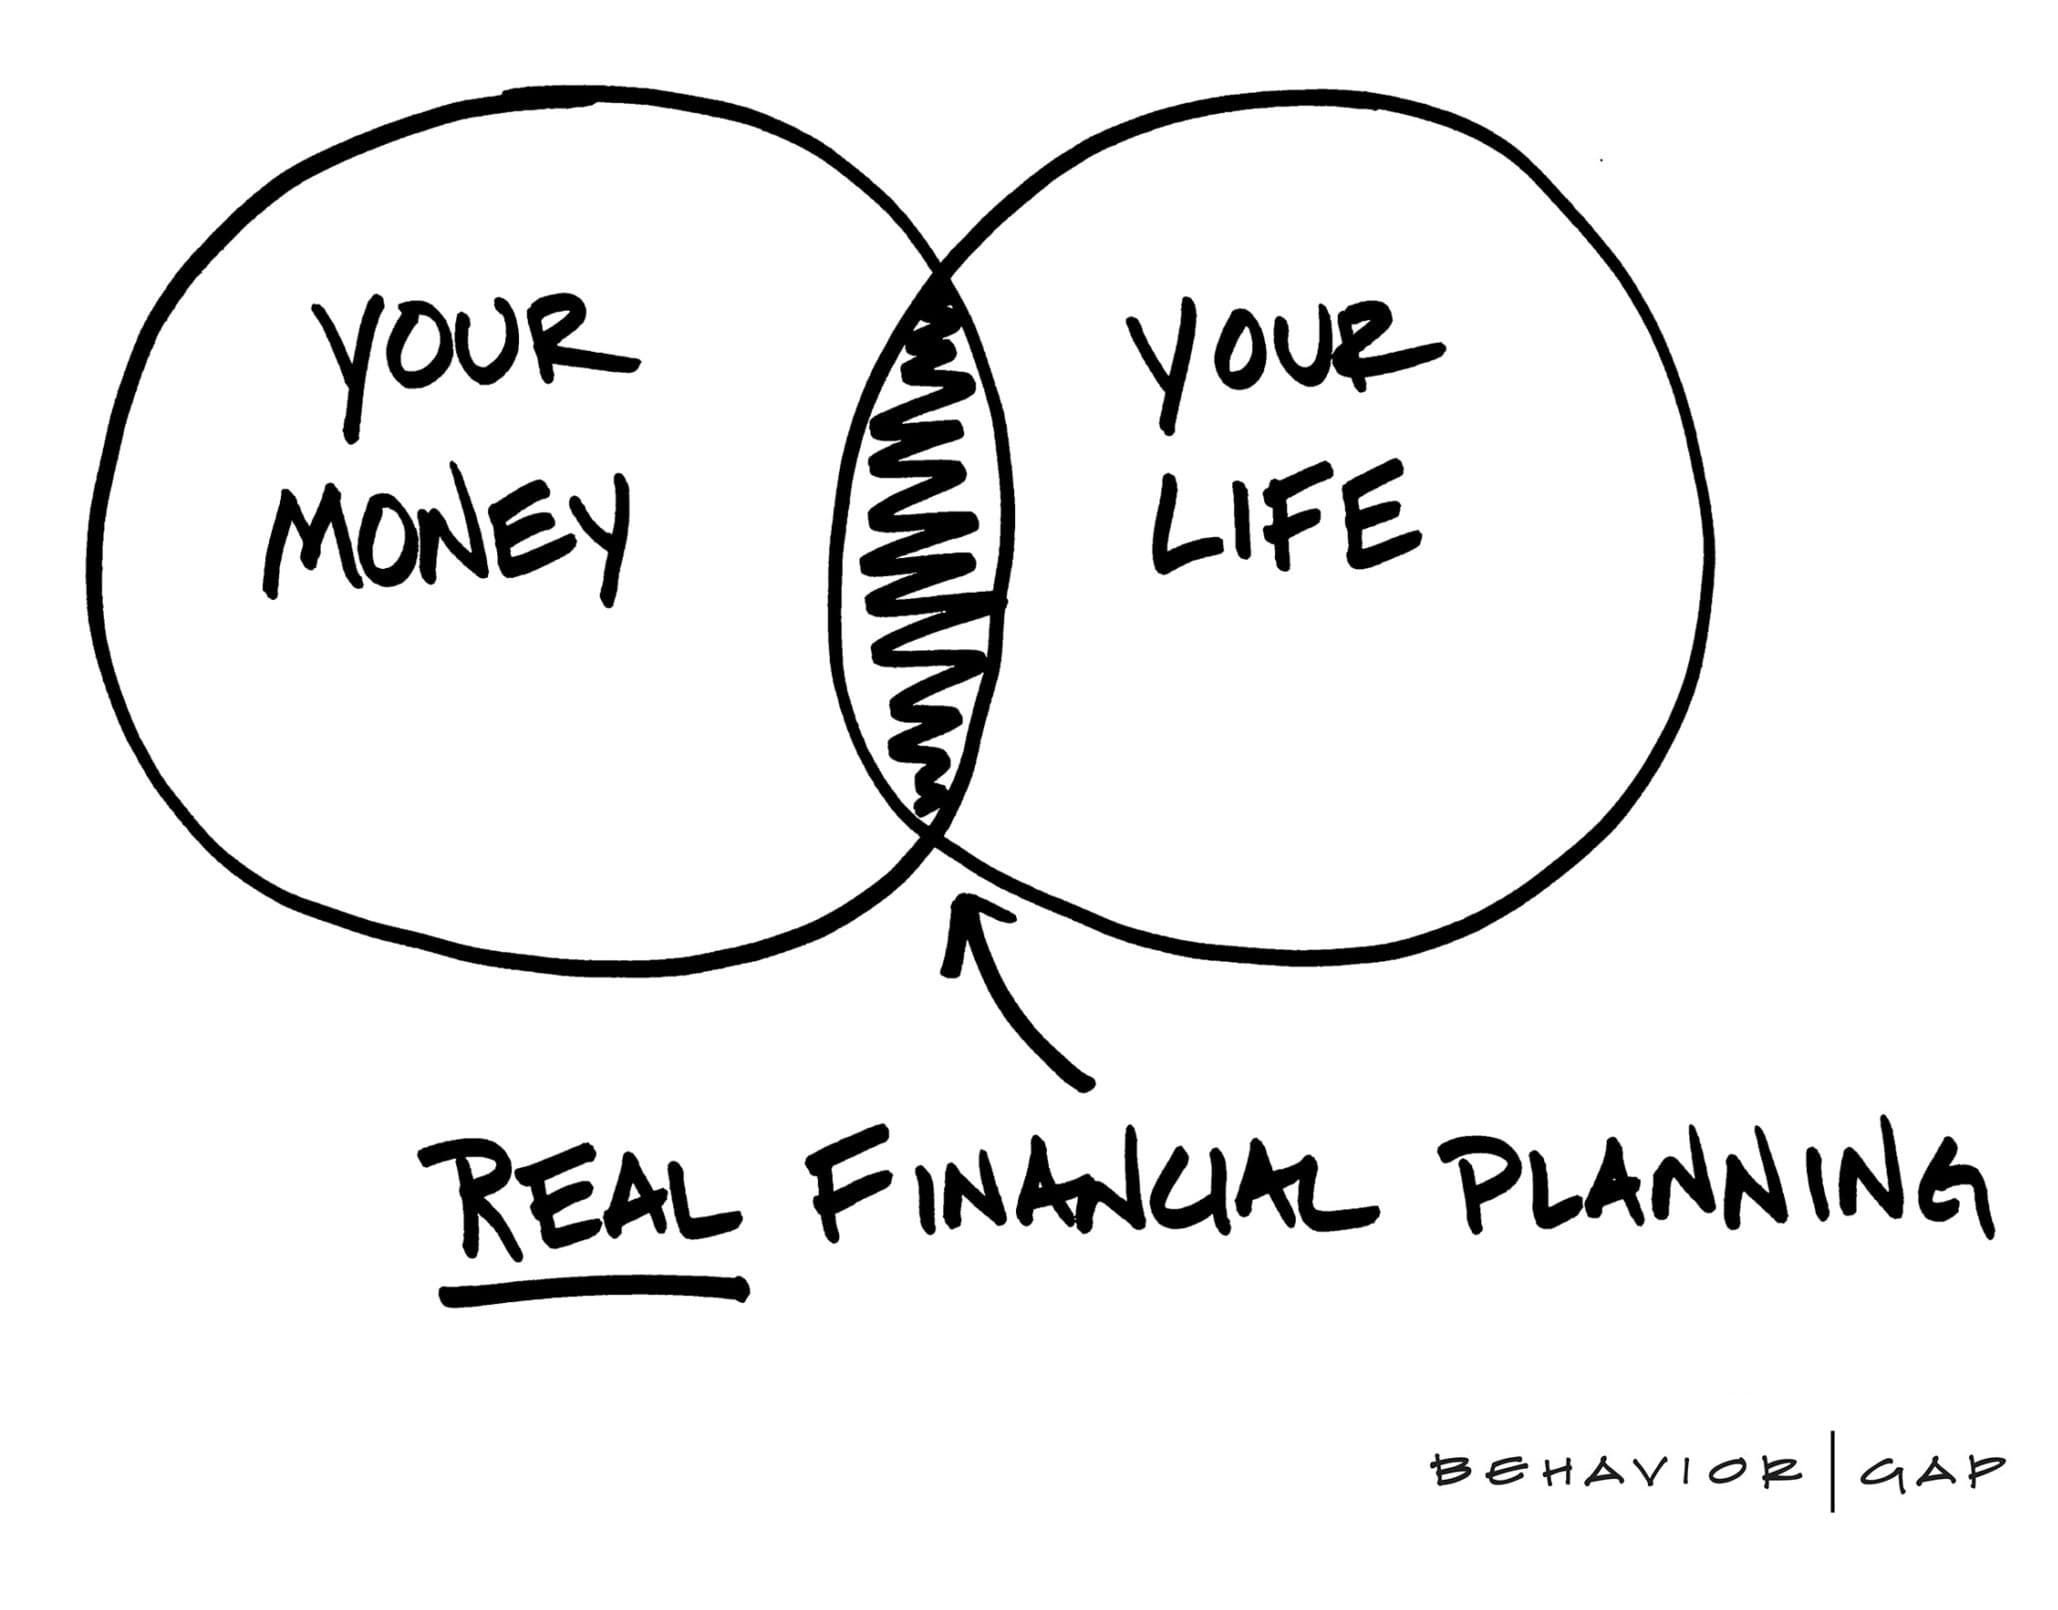
I believe effective financial planning happens where your money and your life meet. That is where a plan can make real, lasting improvements, which is why every engagement starts with your goals before it gets to your accounts.
Advice-Only Planning, Billed by the Hour
Every service on this page is part of one hourly engagement. I give the advice, you keep control of your accounts and implement the recommendations, and you pay $395 per hour only for the planning work we do.
I don’t manage new clients’ investments, sell insurance or other financial products, or prepare tax returns.
Retirement Savings & Income Planning
Retirement income planning answers the questions most people bring to a first call: Can I retire, and when? How much can I spend each year? How do I turn savings into a paycheck?
I look at your cash flow, savings, Social Security, pensions, and investment accounts together. Then I recommend a sustainable spending level, a Social Security claiming strategy, and the order to draw from taxable, tax-deferred, Roth, and cash accounts.
- Cash flow planning
- Retirement income strategies
- Tax-efficient withdrawal strategies
- Social Security claiming, including spousal and survivor benefits
- Work-optional and early retirement questions
My preferred approach to retirement income is a simple two-bucket strategy that is easy to understand and implement. If you prefer another method, such as buckets, ladders, guardrails, or a set percentage, I will listen, give you my opinion, and plan around the approach that fits you.
Investment Planning
Investment planning sets the allocation, account locations, and holdings your plan calls for. You place the trades in your own accounts.
Using what I learn in our conversations, I develop an allocation target guided by your objectives and tax situation, and that target guides every portfolio decision. I believe strongly in a passive approach: simple portfolios built with low-cost, total market index funds. A highly diversified portfolio can often be built with just 1 to 4 exchange-traded funds (ETFs), which are usually more tax-efficient than mutual funds.
Your assets can be held anywhere you like. Many clients consolidate old 401(k)s, TSPs, 403(b)s and IRAs to make tracking and implementation easier, but that choice is yours.
- Asset allocation, including how it should change as retirement approaches
- Asset location
- Tax-efficient investing
- Simplifying and consolidating accounts
- Concentrated, employer, or individual stock positions
Income Tax Planning
My income tax planning looks forward. Tax preparers generally look backward, reporting to the IRS what happened last year. I focus on multi-year strategies to minimize your expected total lifetime income tax liability.
- Roth IRA conversions
- Tax bracket management
- Required minimum distributions (RMDs)
- Medicare premium surcharges (IRMAA)
- Charitable donations
- How Social Security, Roth conversions, and taxes interact
I don’t prepare or file tax returns. I am glad to collaborate with your tax preparer or CPA, and I can suggest firms you might consider if you need one.
Risk Management & Insurance Planning
Insurance planning starts with a review of your existing policies. Then I may recommend changes to your current coverage or new coverage.
- Health insurance, including coverage before Medicare
- Disability insurance
- Life insurance
- Long-term care insurance
- Property & casualty and umbrella coverage
You cannot purchase insurance products through me. I can refer you to trusted companies, or you can work with insurance companies you already do business with.
Estate Planning (Limited)
My estate planning guidance is intentionally limited. I briefly review the estate documents you already have, mainly to understand your trusted contacts and the relationships that matter to your plan.
Beyond that, my advice covers best practices: documents you might consider having and the importance of listing beneficiaries correctly on every account. I see myself as an accountability partner who encourages you to have a plan in place. Qualified estate attorneys draft documents and give expert advice, and I am happy to work with yours.
What the Initial Engagement Includes
- 2 to 3 collaborative meetings, by video call and/or in person
- Setup of and access to RightCapital planning software
- A written Executive Summary, typically 5 to 10 pages, with bulleted, action-oriented recommendations
- One additional month for follow-up questions and guidance as you implement
Questions About My Services
Yes, you retain 100% control. Your assets can be custodied anywhere you like. While many clients choose to consolidate accounts to make tracking and implementation easier, it is entirely up to you.
In tax-advantaged accounts (like IRAs), you could rebalance immediately since there are no tax consequences. In taxable accounts, we’ll likely want to prioritize reducing concentrated positions over time to manage the income tax impact. A specific plan would be discussed during an Initial Engagement.
No, I do not prepare or file tax returns.
Yes, absolutely. I could also suggest other firms you might consider, if interested.
No.
Have a Question About a Service?
The FAQ page answers the questions prospective clients ask most, from Roth conversions to who implements the plan.